Barclays Sees Two Key Drivers Behind A Potential Tesla Q3 Delivery Beat
Tesla is expected to report third-quarter earnings in late October.
Ahead of the release, Barclays autos analyst Dan Levy expects deliveries to "beat" consensus, driven by two key factors: stronger Full Self-Driving adoption and rising exports from Shanghai.
FSD
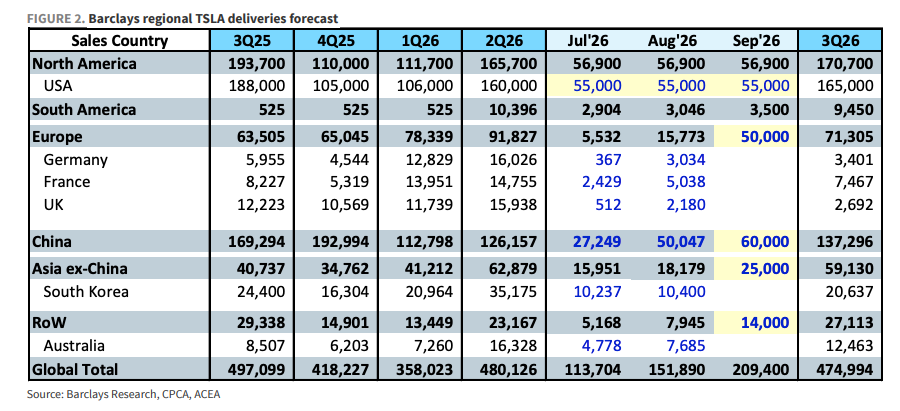
First, FSD uptake is increasingly relevant - not only in serving as the "consumer AV" element of Tesla's AV push, but also in providing both a margin boost, and perhaps more importantly a volume boost to Tesla. Indeed, Tesla's 2Q delivery beat was in part driven by North America, and we assume that with FSD uptake of 55% in the quarter, buyers are increasingly choosing Tesla because of FSD.
Asia Demand
Tesla is increasingly benefiting from its China exports. In our visit to Giga Shanghai last week as part of our China Autos fieldtrip (see here and here), we were reminded of Tesla's significant cost advantage in Shanghai. We believe exports from Shanghai may be at least 20% of Tesla's global volume this year, and many rest-of-world markets which had previously been afterthoughts (i.e. Australia, Colombia, Asia ex-China) are now providing key volume boosts.
Levy estimates Tesla will deliver about 475,000 vehicles, above Wall Street consensus of roughly 466,000 and above his previous forecast of 450,000. However, that would represent a decline of about 4% from a year earlier and 1% from the second quarter.
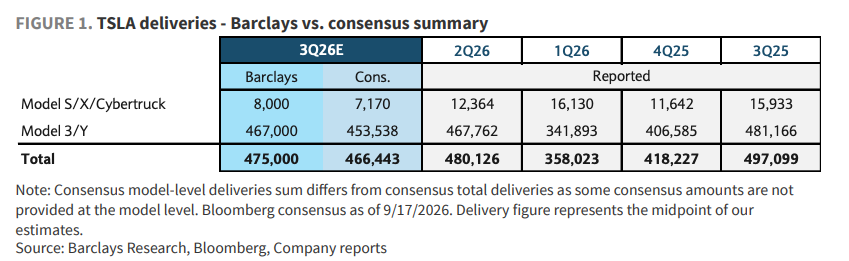
Tesla is tracking toward 1.8 million deliveries for this year, up 10% from last year but back to its 2023 peak.
"We believe a solid 3Q deliveries result would be a further validation point that Tesla's vehicle growth has inflected positively, which became more evident after the significant 2Q delivery beat (480k vs cons 406k). Recall, at 2Q mgmt noted Tesla exited the quarter with its largest backlog since 2023, implying the potential for further growth ahead. We now turn to 3Q commentary for reads as to whether mgmt continues to see robust demand ahead," Levy said.
Barclays regional TSLA deliveries forecast
Levy pointed out that a delivery beat would not translate into stronger margins. He expects automotive gross margin, excluding regulatory credits and including stock-based compensation, to remain flat or edge below the second quarter's 16.3%.
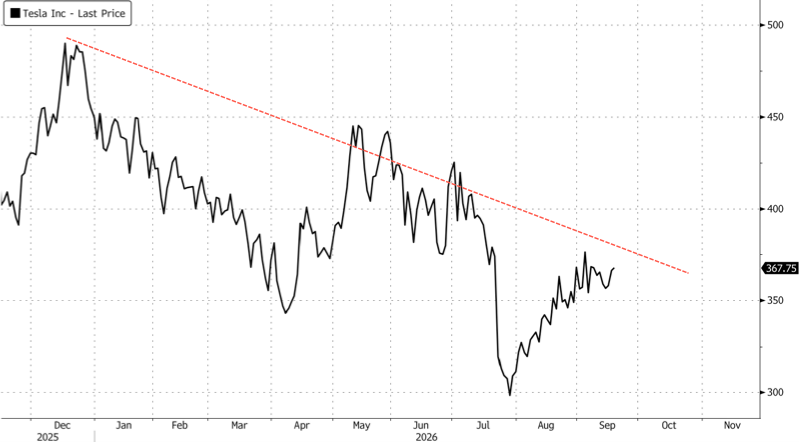
Tesla shares have slumped 18% year to date as of early Friday morning.
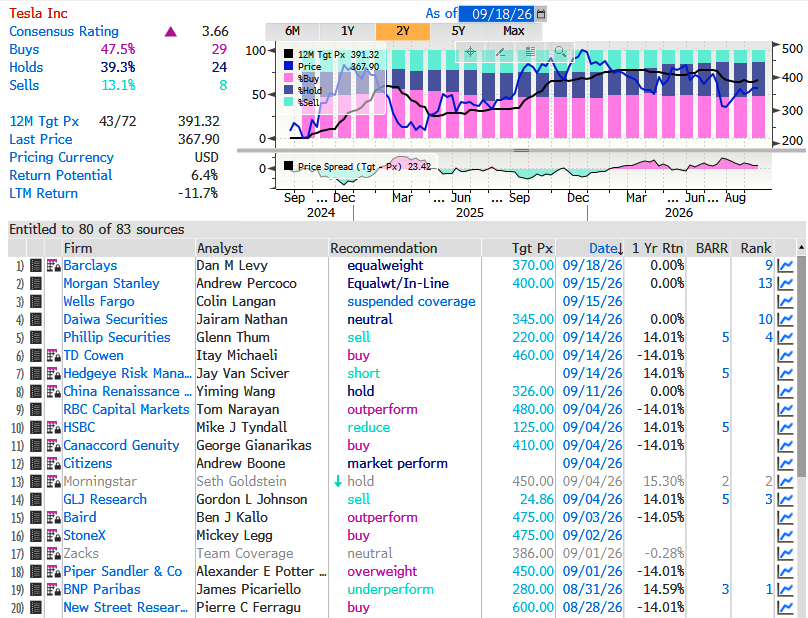
Wall Street analysts tracked by Bloomberg have assigned 29 "Buy" ratings, 24 "Hold" ratings and 8 "Sell" ratings, with an average 12-month price target of $391.
Looking ahead, there has been Tesla-SpaceX merger rumors this summer (read full report).