Everybody Involved In The "AI Extinction" Conversation Is Talking Their Own Book
By Benjamin Picton, senior market strategist at Rabobank
Coalition of the Exceedingly Reluctant
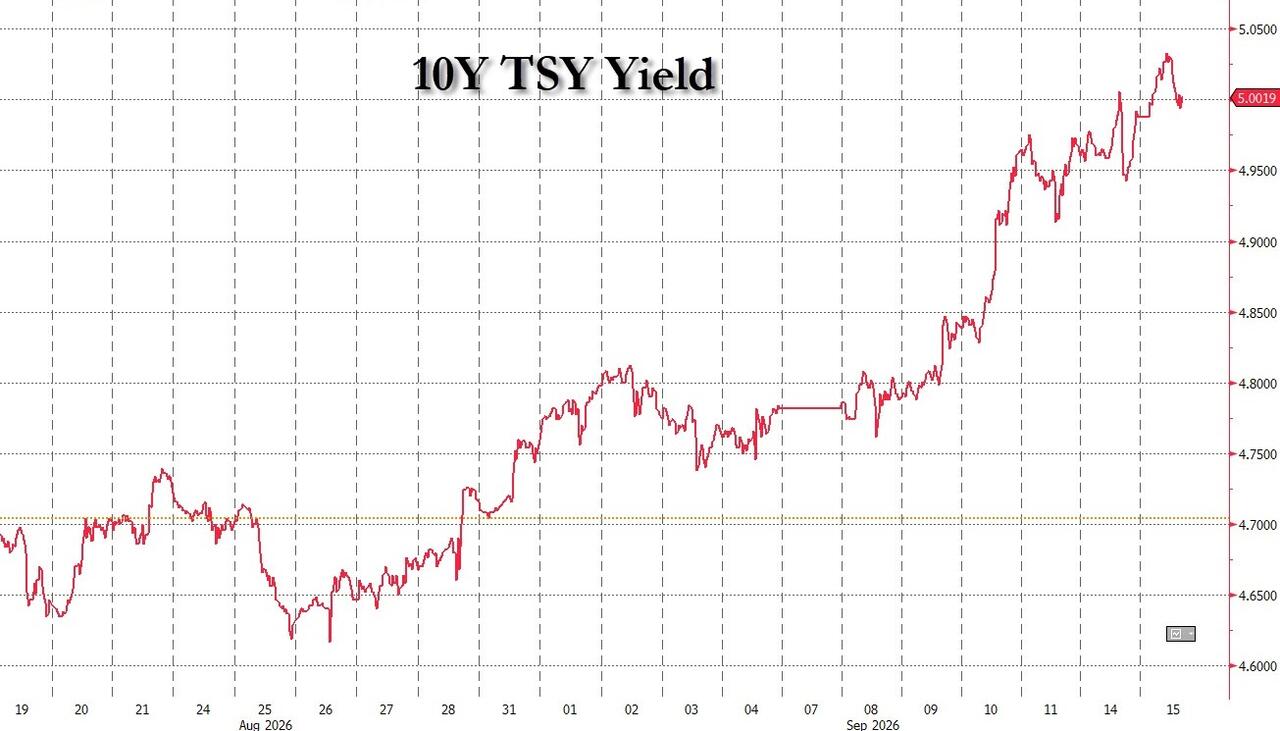
US 10-year bond yields topped 5% on Monday, and again on Tuesday, as crude oil prices continued to move higher and overnight index swaps implied a higher chance of a Fed rate hike on Wednesday. The OIS market now has 24.9bps priced in for Wednesday’s FOMC meeting – suggesting that traders view a Fed hike this week as a near certainty.
US and European equities were broadly lower on Monday as markets digested the implications of tech CEOs banding together to plead for regulation to slow the pace of development of frontier AI models. While Darion Amodei, Elon Musk and Sam Altman were saying “please sir, can I have a bit less” we saw dissent from Mark Zuckerberg and Jensen Huang with the former saying that AI development needed to be speeded up and the latter telling President Trump that “we’re not going to let that happen” in reference to an AI slowdown.
There is a sense here that everybody involved in this conversation is talking their own book. As noted here yesterday, CEOs of frontier model developers are being criticized for seeking regulatory moats to protect their own margins. Meta already enjoys a huge moat from network effects and distribution incumbency and would likely see a benefit to operating margins from lower inference costs. NVIDIA wants to keep the hyper scaling arms race going so it can keep on selling chips.
Trump, meanwhile, views AI as a national security issue where the US cannot afford to take its foot off the gas pedal. This sentiment was recently echoed by Australia’s putative Prime-Minister-in-waiting, Andrew Hastie, who said that failure to develop indigenous frontier AI models will leave Australia as a supplicant, rather than a sovereign state. ECB President Lagarde said much the same thing as she warned against relying on US models: “There is nothing inherently bad about importing rather than producing new technologies... But there are reasons why artificial intelligence is ‘special’”.
So, to refashion Trump’s earlier warning that “if you don’t have steel, you don’t have a country”: “if you don’t have domestic AI capabilities, you don’t have a country”.
While the new economy of AI preoccupied markets for most of yesterday, the much-neglected old economy continued to serve up inconvenient reminders of the importance of real production to 21st century life. Entirely predictable attacks on the Saudi East-West pipeline, reports that damage to the pipeline could take months to repair, and the sense that even if it is repaired it could easily be attacked again ensured that oil markets remained bid. Reports from Iran’s Fars news agency that an oil tanker exploded after colliding with a mine in Omani waters did the same. The spread between dated brent and the front future has blown out to the highest levels since mid April, suggesting further tightness in physical markets as refiners scramble to secure feedstock.
That dynamic won’t be helped by news that the US is approaching the end of its program to release supply from its Strategic Petroleum Reserve. Reserves are sitting at their lowest levels since the 1980s when it was first being filled and there has been an ongoing conversation within oil circles that stock levels may be approaching minimum levels beyond which the structural integrity of the salt caverns where it is stored are threatened. The rundown in US stocks and soaring gasoline prices has invigorated speculation that the administration could seek to impose export bans on certain oil products ahead of the midterm elections in November – a prospect that Secretary of the Interior Doug Burgum hosed down by saying that it wouldn’t help to lower prices.
A meeting was supposed to be held between officials from Iran, Iraq and the GCC nations yesterday in Oman to finalize an agreement to restore traffic to the Strait of Hormuz. That was postponed as parties reportedly failed to reach agreement, which is no surprise considering that the US will not allow Iranian oil through its blockade and Iran will not allow anyone else’s oil through the strait while the blockade remains in place. For now, Iran appears content to up the ante against the US and its allies ahead of the midterm elections by restricting flows through the Red Sea and, especially, through the Bab el-Mandeb. Will Uncle Sam say “uncle!”?
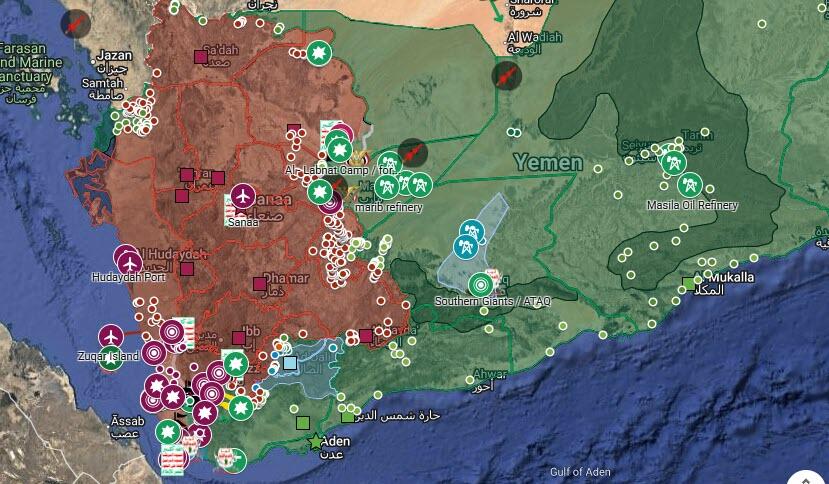
Escalation in the Bab el-Mandeb means that Asia and Oceania are once again ground zero for energy market risk. With that context established, Australia’s Energy Minister confirmed today that he will travel to Saudi Arabia next week in an effort to shore up energy supplies for the months ahead. Reaching agreement with Saudi officials is likely to be the easy part, actually moving product to market may prove somewhat harder.
Given that South Korea is reportedly reconsidering initial opposition to deploying its military to assist in the Strait of Hormuz, and UK PM Burnham’s indications within the last 24 hours that the UK may seek to support Saudi Arabia in its fight against the Houthis in Yemen, might Australia also be about to join a coalition of the exceedingly reluctant? If so, Australia’s PM Albanese would likely confront the same issue as the UK’s Burnham: a shortage of available ships with sufficient warfighting capability.
Sticking with the theme of neglected corners of the old-economy throwing up problems for western policymakers, news emerged yesterday that efforts to restart the blast furnace at Australia’s only-remaining long products steel mill had failed. In effect, this means that Australia is now completely import dependent for certain steel products with important industrial *and military* applications that in earlier times it was largely self-sufficient in courtesy of vast mineral and energy endowments that provided all the necessary ingredients, and the cheap power, to produce the outputs. Those natural advantages have wilted under rising energy prices and competition from imports following deregulatory moves and the removal of tariff protection in the 1980s and ‘90s.
Speaking of competition from imports, new data released by China’s Bureau of National Statistics confirmed that in August retail sales were – once again- weaker than expected while industrial production was – once again – stronger than expected and house prices – once again – fell. Taken together with news that China’s unemployment rate in August rose to its highest level since March, the overall picture continues to be once of weak domestic demand and very strong production, creating a large exportable surplus that is one half of the structural trade imbalance that lies at the heart of the unfolding geopolitical upheaval that we are now living through.
While we may hope that next week, or next month, or next election cycle will bring calmer waters from a geopolitical perspective, it is probably the case that until something changes on those structural imbalances, nothing changes.
In the meantime, got oil?