Futures Flat As Oil, Yields Drop Ahead Of Trump UN Address
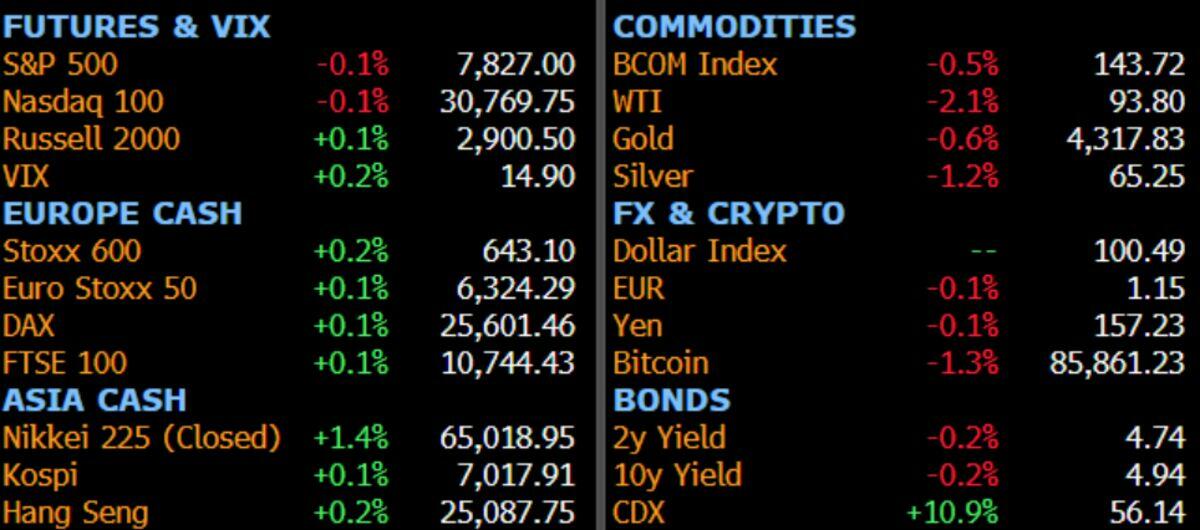
Futures are flat, having recoverd a modest drop after the European open, following yesterday’s strong, positive performance despite energy prices and yields being lower for a second consecutive day. As of 8:00am ET, S&P and Nasdaq futures are fractionally in the green after an advance in tech giants and chipmakers drove the index to a one-month high. In premarket trading, semis are down ~60bp after a blistering 5-day run that added 11.2%. Memory names are weaker as Mag7 and Software remain bid. Alibaba ADRs (BABA) gain 3% as the company is rolling out what it calls China’s most powerful AI chip, an accelerator to compete with Nvidia Corp. Brent crude erased gains of as much as 2% to fall toward $98 a barrel. The reversal came after Japan’s Kyodo News Agency reported that Iran has proposed to reopen Hormuz within seven days if the US blockade is lifted. While Iran has since denied this report, a separate report that Saudis may restart the East-West pipeline helped sentiment. Treasury yields turned lower, with the 10-year rate down two basis points to 4.93%. The dollar barely budged while the entire commodity complex is lower, though Base Metals are a bid. These moves likely reflect growing optimism around a diplomatic solution in the Middle East and improved US / China relations, which combined will support AI and lower energy prices, and potentially lower tariff rates. Today’s macro data focus is on ADP’s weekly number, regional Fed activity indicators, and another Fedspeaker. Looking ahead, highlights include UN Meetings: UN General Debate including Trump, Macron, Burnham; Trump-Zelensky meeting; Trump-Burnham meeting; Trump-Gulf Leaders meeting.
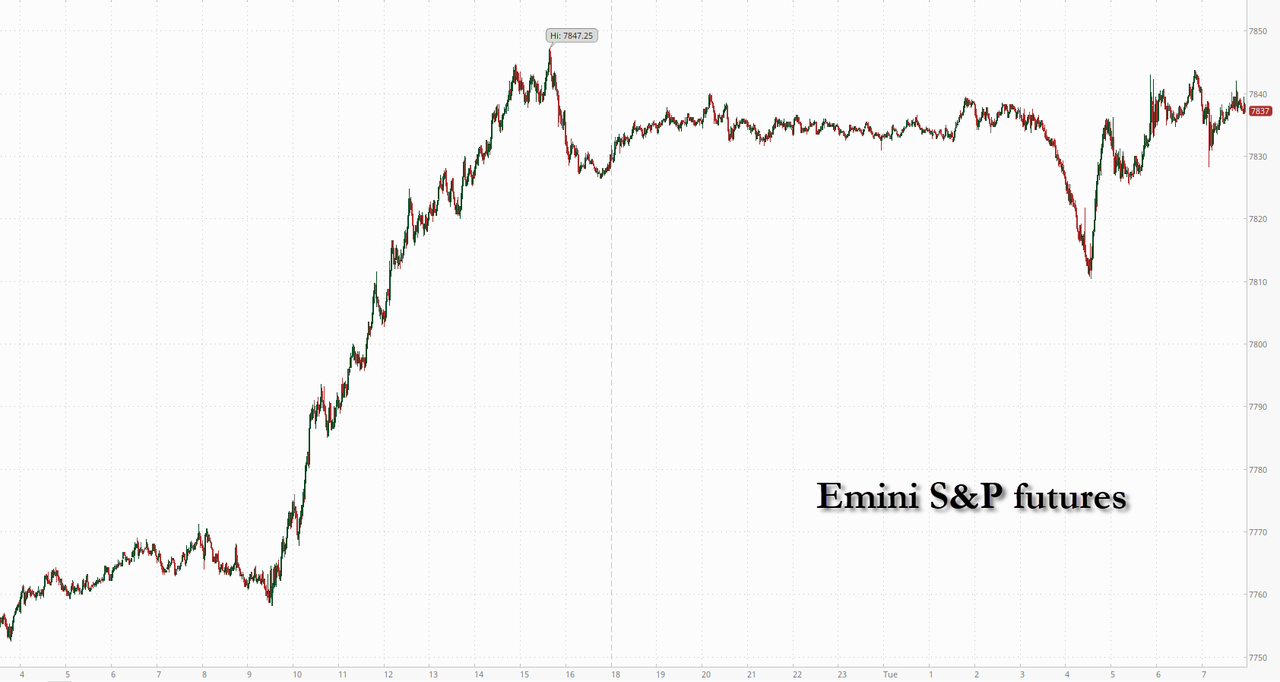
In premarket trading, Mag 7 stocks are mixed: Alphabet +0.5%, Amazon +0.4%, Apple +0.2%, Meta -0.7%, Microsoft +0.8%, Nvidia -0.2%, Tesla +0.7%
- Alibaba ADRs (BABA) gain 3% as the company is rolling out what it calls China’s most powerful AI chip, an accelerator to compete with Nvidia Corp.
- GameStop (GME) rises 4% after CEO Ryan Cohen disclosed a $26.4 million stock purchase in a filing with the Securities and Exchange Commission.
- Grab (GRAB) rises 6% after Chief Executive Officer Anthony Ping Yeow Tan disclosed a $29.9 million stock purchase in a filing with the SEC.
- Quest Diagnostics (DGX) falls 6% after the Centers for Medicare & Medicaid Services released new preliminary medicare payment rates for lab services.
- Vicor (VICR) jumps 9% after the power equipment company raised its third-quarter revenue growth guidance, citing royalties from non-exclusive license to Vertical Power Delivery.
- Viking Therapeutics (VKTX) soars 32% after announcing positive topline results from a study of dosing regimens for maintaining weight loss.
In other corporate news, Roche’s experimental obesity shot enicepatide reduced body weight by 15.5% in trial, potentially ramping up competition with Eli Lilly and Novo Nordisk. On Holding plans to increase constant currency sales at a rate in the high teens through 2029 and ratchet up profitability, as the Swiss brand introduces new products for golf and soccer in its effort to take on Adidas and Nike.
Federal prosecutors are investigating whether Binance, the operator of the world’s biggest crypto exchange, violated US sanctions on Iran by not stopping certain trading on its platform. The newly merged Paramount Skydance and Warner Bros. will be headquartered in Los Angeles, CEO David Ellison said.
Stocks are set to for a breather after the strongest session since early August. Positive geopolitical developments and a new lease of life for the AI trade made Monday an easy win, but questions remain on both fronts. Crude prices reversed earlier gains after Kyodo reported, citing an Iranian official, that Iran has suggested to the US administration that it will open the Strait of Hormuz within seven days if the US lifts its blockade on Iranian ports and stops military operations related to Hormuz. Alongside the Kyodo report were constructive comments by the IRGC, stating that if Iran’s national interests require negotiations alongside war, then it must negotiate. Elsewhere, Saudi Arabia was testing a restart of its East-West pipeline, according to a person familia with the matter, offering another potential boost to supply. Brent has returned below USD 94/bbl on the above headlines. A constructive risk tone followed, with equity futures and fixed income rising while the USD weakened.
President Donald Trump is set to address the United Nations General Assembly in New York later Tuesday, with traders watching for a possible meeting with his Iranian counterpart that could prove pivotal.
AI-linked stocks were mixed after a positive reception for Meta Platforms Inc.’s new AI agent fueled broad gains in the previous session. Microsoft Corp. rose 0.9% in premarket trading to lead gains among the Magnificent Seven. An exchange-traded fund tracking chipmakers was slightly lower.
Monday’s price action showed that AI FOMO is still a big driving force in the market. One indication appears in call to put skew on a 10% move in SPX over the next month. That skew metric is at its highest since late August, hovering just below its year-to-date high. The sentiment is across asset classes, with SoftBank said to have drawn more than $20 billion of preliminary demand for its junk bond deal to help fund investments in OpenAI.
The swings in sentiment after Monday’s rally highlighted how confidence in the AI trade remains vulnerable to macroeconomic risks. Bond yields remain near their highest levels in years despite easing this week, as traders continue to price in imminent interest-rate hikes and persistent fiscal shortfalls.
“I don’t see anyone shorting tech and AI before the third-quarter earnings season begins,” said David Kruk, head of trading at La Financiere de l’Echiquier in Paris. “There’s also some hope that Trump will find a way to lower oil prices before the midterms. It makes sense that the market consolidates slightly.”
The strong early uptake of Meta’s Muse AI agent revived hopes of agentic AI coming to the mainstream consumer market, with more insights expected during Zuckerberg’s keynote speech at Meta Connect tomorrow night. Elsewhere in AI, Alibaba rolled out what it called China’s most powerful AI chip, an accelerator to compete with Nvidia and underpin a massive expansion of data center capacity in coming years. Tencent launched its latest image-generation model. Headlines may also come from Amazon Accelerate over the next few days.
Still, angst about the data center buildout continues, with Texas Governor Greg Abbott halting all permits sought by data centers until an audit of risks to the grid is complete. Texas is home of one-fifth of the US’s data center pipeline in terms of IT power capacity, by far the largest of any single state.
Global investors are also gearing up for the summit between Trump and Chinese President Xi Jinping later this week. Officials from the two sides wrapped up their second day of talks in New York on Monday as they sought to advance negotiations ahead of Xi’s visit to the US. For markets, the big question is what happens when the yearlong trade truce expires in November, noted Jim Reid at Deutsche Bank AG. While the tone between the two sides remains positive, they have yet to reach an agreement.
“Given increasing geopolitical uncertainty worldwide, keeping the world’s two dominant economies on speaking terms has rarely mattered more,” said Roman Ziruk, lead FX strategist at Ebury.
In trade, Vietnamese President To Lam said his nation is “very close” to a deal with the US as he pledged to buy more high-tech goods to narrow the trade gap. Canada’s trade minister said talks with India are “moving along really well” as his country looks for new markets amid a tariff war with the US. Meanwhile, China’s expansion in the rare-earth supply chain could help provide Xi leverage over the US during their talks.
The Stoxx 600 briefly touched a session high too and is up by around 0.2%, rising on Tuesday as oil drops, with tech shares also fueled by optimism around artificial intelligence developments. Retail and consumer shares are the best performers. Energy and insurance fall.
Stoxx 600 gains 0.2% to 643.25 with 200 members down, 390 up and 10 unchanged. Here are some of the biggest movers on Tuesday:
- Bureau Veritas rises as much as 2.1% after saying it expects double-digit revenue growth over 2027-2028 and aims to deliver €1 billion from AI-driven markets by the end of the decade.
- Kingfisher shares rise as much as 11% after the B&Q and Screwfix owner posted a first-half earnings beat and lifted its full-year profit guidance beyond analyst expectations.
- Vusion shares rise as much as 11% after the French maker of electronic labels for retail stores reported first half results that included an almost 50% increase in adjusted Ebitda.
- Verbund gains as much as 5.1%, while ERG is up as much as 2.9%, after Bank of America upgraded both to neutral from underperform.
- Smiths Group gains as much as 6.4% with analysts generally positive on the UK manufacturing equipment firm’s performance in 2026, and its outlook for 2027.
- Buzzi shares fall as much as 5%, to the lowest since January 2025, as UBS downgrades the Italian construction materials firm to sell from neutral, warning that import pressure and CO2 allowance costs could drive sharp earnings downgrades.
- UBS shares fall as much as 4.1% after CEO Sergio Ermotti says year-on-year transactions in wealth management and banking fee pool are likely down in 3Q.
- Ericsson slips as much as 4.3% after Morgan Stanley downgrades the Swedish mobile networks and technology group to underweight from equal-weight, saying margins are “inflecting to the downside.”
- Industrie De Nora tumbles as much as 14% after investor Snam offloaded a chunk of shares at a hefty discount to the last close. The stock has slipped below the offer price.
Asian stocks advanced for a fifth day, as technology sector gained amid optimism over Meta Platform Inc.’s new personal agent. The MSCI Asia Pacific excluding Japan Index jumped as much as 1.5% before paring about half of those gains. Taiwan’s Taiex climbed to a record before erasing most of the advance. Korea’s Kospi closed 0.2% higher, while Japan remained shut for a holiday. In FX, the Bloomberg Dollar Spot Index fluctuated, and is now flat. The yen wiped out its decline, with USDJPY briefly slipping below 157. Tencent shares jumped 5%, as positive feedback on Meta’s new personal agent unleashed investor optimism that the Chinese social media giant may unlock similar AI‑driven optionality through its WeChat ecosystem. Alibaba gained 2% after it rolled out an AI chip and announced plans to expand data center capacity over the coming years.
In rates, treasuries hold modest gains after erasing losses during European morning following a sharp drop in oil prices. US yields are about 2bp-3bp richer across the curve led by the belly, steepening 5s30s spread by around 1bp. 10-year, near session lows around 4.93%, keeps pace with German counterpart and trails UK by about 1bp. European bond yields shifted direction on the slide for crude, with 10-year yields down by about a basis point in the US, Europe and the US, having been pushing higher through the first portion of the session. 2-year note auction at 1 p.m. has WI yield near 4.75%, about 55bp cheaper than last month’s, which stopped through by 0.4bp; $70 billion 5-year and $44 billion 7-year note auctions follow over next two days. IG dollar issuance slate includes a few offerings so far. Nine were priced Monday totaling around $10 billion, with issuer paying about 3bp in new issue concessions on deals that were 3.4 times covered. US session includes $69 billion 2-year note auction, the first of this week’s three coupon sales, with additional supply pressure possible from Sysco Corp. jumbo multi-currency bond offering.
In commodities, crude futures fell on signs of diplomatic efforts to reopen the Strait of Hormuz - driven by a Japanese media report on a possible early reopening of the Strait of Hormuz - and as Saudi Arabia sought to reopen a pipeline Brent is sitting just below $100/bbl while WTI has slipped below $94. Gold fell below $4,300 but recovered some ground, though is still off for the day.
US economic data slate includes ADP weekly employment change (8:15 a.m.), September Philadelphia Fed non-manufacturing activity (8:30 a.m.) and September Richmond Fed manufacturing index (10 a.m.). Fed speaker slate includes New York’s Williams (10:05 a.m.), Vice Chair Jefferson (10:20 a.m.) and Richmond’s Barkin (1 p.m.)
Market Snapshot
Top Overnight News
- Brent crude dropped below $100 on a Kyodo report that Iran could reopen the Strait of Hormuz if the US lifted a blockade of its ports. Futures whipsawed. Iran’s Revolutionary Guard said it must negotiate if it’s in the national interest to do so. BBG
- Several Asian refiners have been told informally by Saudi Aramco they will soon be able to pick up oil from the Red Sea port of Yanbu. Loadings from Yanbu have been all-but-halted since the East-West pipeline was closed after being attacked by drones launched from Iraq on Sept. 10. BBG
- China's Xi Jinping is expected to press US President Donald Trump to halt Taiwan arms sales under a 1982 joint statement during a visit to Washington this week, which he could do at the US National Archives, sources briefed on the matter said. BBG
- Alibaba unveiled what it called China’s most powerful AI chip, an accelerator to rival Nvidia and underpin a massive expansion of data center capacity. BBG
- Saudi Arabia spent months rerouting oil across the desert to circumvent the Strait of Hormuz. Now, with its Red Sea bypass route disrupted by attacks, the world’s oil kingpin is having to return to the waterway it was trying to avoid in the first place. Saudi Aramco, the country’s state-controlled oil giant, is loading more oil onto tankers in the Persian Gulf and then taking its chances sending them through the Strait of Hormuz. WSJ
- Republican lawmakers are ratcheting up pressure on Donald Trump to ban diesel exports as surging prices squeeze American farmers and truckers just weeks ahead of pivotal midterm elections. FT
- SoftBank drew more than $20 billion of preliminary demand for what’s shaping up to be one of the biggest junk bond deals ever. BBG
- Trump's approval rating fell to 32% - the lowest of his political career - as his fellow Republicans soured on his handling of the cost of living amid the unpopular Iran war. RTRS
- US office real estate is entering a new phase as billions in maturing debt force owners and investors to confront losses. Office CMBS delinquencies are near a record 12%, with almost $40 billion of debt maturing this year and next already troubled. BBG
Iran War
- A Senior Iranian Official said that Tehran welcomes the revival of diplomacy if the US takes tangible steps, stating that the Iranian delegation is in the US and has full authority to revive diplomacy in the US, Reuters reported. The official added that details of an agreement to end hostilities with the US can be discussed in New York via mediators. Furthermore, the official said the proposal was delivered to the US via mediators on September 16th while reiterating the Kyodo report that Iran can reopen the Strait within seven days if the US eases military pressure and lifts the blockade.
- Iran has reportedly suggested to the US administration that it will open the Strait of Hormuz within seven days if the US lifts its blockade on Iranian ports and stop military operations related to Hormuz, Kyodo reported citing an Iranian official. The official added that the proposal called for renewed talks aimed at reaching a permanent end to hostilities between the two countries. Furthermore, the official went on to say that there is a possibility of moving toward an agreement, but the US must demonstrate "seriousness and commitment" if diplomacy is to advance.
- IRGC said that if Iran’s national interests require negotiations alongside war, then it must negotiate but it will respond to any enemy strike with multiple strikes across different arenas and in various ways, Al Jazeera reported. To add, the IRGC said it will have no contact with the US as a military institution, even if Washington requests it and its assessments indicate the US and Israel are not prepared for a new war, but Iran is ready if they miscalculate.
- US President Trump said he had meetings regarding Iran and that Iran is not doing well.
- Iranian Parliament Speaker Ghalibaf said US President Trump cannot impose his power on Iran, adding that Iran will neither shut down nor surrender. Ghalibaf went on to say that missile technology is at a stage where Iran can "target anywhere it decides" and they will never yield in the conflict.
- Iran's Judiciary Spokesperson said Iran has full control over the Strait of Hormuz, SNN reported.
- Iran's Foreign Ministry said introducing Iran as a cause of fuel price hikes is merely a sign of the US administration's evasion of responsibility for consequences of military aggression against Iran.
- G7 issued a statement on the Middle East which noted the situation in Yemen poses an unacceptable threat to the stability and security in the region and to global energy security, while it condemned in the strongest terms the unacceptable continued strikes carried out by the Houthis in Yemen and against Saudi Arabia. It called on the Houthis to immediately cease all military actions, threats and attacks against civilian shipping, as well as called on Iran to end its arming of and support for the Houthis, which it noted violates UN Security Council resolutions. Furthermore, it stated that Iran's reprehensible actions constitute a dangerous pattern of escalation and risk further exacerbating the conflict.
- Israeli Defence Minister said they will bomb Iran for the 3rd time if necessary until the regime is overthrown, Al Arabiya reported.
- French President Macron said he had a constructive discussion with US President Trump on the Red Sea and Ukraine.
- UK PM Burnham agreed for the UK to provide Saudi Arabia with defensive air-to-air refuelling, with the support to begin in days and last for weeks.
- EU's Kallas said the EU naval mission in the Red Sea requires additional naval and air resources, while she added the EU would need more than 10 ships in the Red Sea.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks mostly gained following the advances on Wall Street, where the Nasdaq outperformed and notched a record close as Meta shares surged over 11% on strong adoption of its Muse AI agent and with AMD joining the USD 1tln market cap club, while markets in Japan were closed again for the holidays. ASX 200 traded marginally higher but with gains capped as the strength in tech, consumer discretionary and health care was partly offset by losses in utilities, energy and financials. KOSPI took its cue from the tech and communications outperformance stateside, while South Korea's Industry Ministry noted that the final announcement on the US investment plan will be made by President Trump, with the funds to be remitted within 45 days if requested by the US. Hang Seng and Shanghai Comp were positive as tech stocks led the advances in Hong Kong, although some property, energy and biopharmaceutical stocks lagged while participants also continue to await the Trump-Xi summit this week.
Top Asian News
- RBA Governor Bullock said supply shocks are difficult for monetary policy to deal with and that policy needs to deal with second-round effects on inflation, while she stated that the current decline in house prices is consistent with past episodes and that unemployment at 4.5‑5% is likely to reduce inflation pressure. Furthermore, Bullock said she is not signalling anything on policy, and it is up to the board, as well as noted that inflation risks are materialising from the Middle East and excess demand at home.
- RBNZ Governor Breman said near-term inflation is expected to be somewhat higher if elevated oil prices persist, while she noted the RBNZ remains focused on the inflation outlook ahead of the October policy decision. Breman also commented that the economic outlook remains subject to significant risks and that current data points to continued economic recovery, though progress remains uneven.
- Alibaba (9988 HK) unveiled its Zhenwu V900 chip, which it said is the most powerful in China with three times the performance of the predecessor, while the Co. targets 20GW of data centre capacity by 2032 and the Qwen team plans to train a new model at a scale of 5tln-10tln parameters.
European bourses were initially lower this morning, but then flicked into the green after a report in Kyodo suggested that Iran could open the Strait of Hormuz within seven days, citing a source. This helped boost sentiment, with crude benchmarks falling to lows, hence weighing on yields. European sectors hold a positive bias. Retail took the top spot, joined closely by Media and Tech. To the downside resides Insurance and Telecoms. Key European movers include: Kingfisher (+8.2%) , raises its FY26/27 adj. PBT guidance; Smiths Group (+4.5%), FY26 revenue raises Y/Y and raises its dividend above estimates; Evonik (+3.3%), reports that BASF explored a potential deal with the Co. earlier in 2026; Bureau Veritas (+1.0%), raises its 2027-28 total revenue CAGR guidance; Ericsson (-3.5%), downgraded to Underweight from Equal Weight at Morgan Stanley.
Top European News
- German Chancellor Merz’s woes cast doubt over the bloc's EUR 2tln budget deal, with his authority in Brussels hobbled by his party’s poor results in regional elections, according to FT.
- UK PM Burnham to call on EU Commission President von der Leyen to allow the UK to partake in the EU's Made in Europe industrial framework, according to the FT.
FX
- Snapshot: The FX space has been exceptionally choppy this morning. Initially, G10s were mixed against the USD, but are now mostly lower, as the USD clambered higher as the session progressed. The Kiwi outperforms after hawkish comments from RBNZ Governor Bremen. She noted that near-term inflation is expected to be somewhat higher if elevated oil prices persist.
- DXY is a touch lower this morning and holds within a 100.30 to 100.66 range. The bias was initially stronger for much of the European morning, before a report in Kyodo, citing an Iranian source, suggested that Iran had told the US admin that it will open the Strait within seven days, if the US lifts its blockade on Iranian ports. This spurred immediate and sustained pressure in the crude complex, weighing on yields and therefore on the USD.
- Following this action, JPY was the largest beneficiary, flicking from red to green within a few minutes. USD/JPY fell from 157.62 to a session trough of 156.85 within a small timeframe – largely thanks to narrowing yield differentials.
- Some may view this move as a bit outsized, given that there is currently no progress to peace at this stage. However, it points out that the mood is a bit more constructive heading into the UN General Assembly, where the Iranian President is set to make an appearance. No sideline meetings are currently expected between the US and Iran, however, the US and Gulf leaders will meet. Any positive mood music following that meeting will no doubt put another bout of pressure on the USD.
Fixed Income
- A bearish start for fixed income, amid initial crude strength and a modest reversal of some of Monday’s action. Gilts underperformed modestly in early-trade, given the unwelcome borrowing data for the UK vs both market and OBR consensus.
- However, this action, of circa. 30 ticks lower in Bunds, five in USTs and over 40 in Gilts gave way to a geopolitical/energy-induced move higher and into the green. After a Kyodo source outlined that Iran has suggested to the US that it would open Hormuz in one week if the US blockade is lifted, alongside a tone change from the IRGC on negotiating with the US if needed.
- This lifted USTs to a 106-09+ peak, firmer by just under 10 ticks on the day. Bunds and Gilts followed, to the upside of 23 ticks and just over 30 respectively. However, as the energy move pauses for breath and updates since the two above have, net, been more bullish for crude, this has unwound with fixed income now near-enough unchanged on the day.
- The day was always headlined by the UN General Assembly, but following the morning reporting, the speeches by US President Trump and Iranian President Pezeshkian tomorrow now draw even greater attention; for any rebuttal of the above, or signs of tangible progress between the sides.
- That aside, BTPs were disappointed by the 2025 deficit/GDP revision, which remained above the key 3.0% mark that determines the EU’s EDP system. As such, we now look to see if Italian Finance Minister Giorgetti moves forward with using the Escape Clause or not. For reference, the BTP-Bund 10yr spread remained steady at 90bps at the time.
- Germany sells EUR 3.735bln vs Exp. 5bln 2.90% 2031 Bobl: b/c 1.21x (prev. 1.56x), average yield 3.28% (prev. 3.09%), retention 25.3% (prev. 22.16%).
- UK sells GBP 4.75bln 4.625% 2032 Gilt: b/c 3.07x (prev. 3.34x), average yield 4.843% (prev. 4.613%), tail 0.4bps (prev. 0.2bps).
Commodities
- WTI Nov and Brent Dec futures have reversed earlier gains and are now sharply lower following a notable shift in tone from Iran, alongside a report from an Iranian source in Japan's Kyodo. First, the IRGC said that if Iran’s national interests require negotiations alongside war, then it must negotiate; this contrasts with the usual escalatory tone of the Iranian Revolutionary Guards. Shortly after the IRGC headline, and adding to the diplomatic mood, Iran reportedly suggested to the US that it could reopen the Strait of Hormuz within seven days if Washington lifts its blockade on Iranian ports, reiterating Iran's conditions for Hormuz concessions. The Kyodo report was later corroborated by a Senior Iranian Source who noted that the Iranian delegation is in the US to revive diplomacy with the US. On the supply front, Saudi Arabia has reportedly restarted the East-West oil pipeline to resume crude oil exports from the Yanbu port.
- Following the above developments, Brent fell from USD 97.70/bbl before the headlines to a USD 93.84/bbl low, while WTI fell from USD 93.14/bbl to a USD 89.40/bbl low. Dutch TTF has followed the broader energy complex lower as the prospect of progress around Hormuz reduces some of the Middle East supply risk premium. The contract has fallen from a EUR 75.22/MWh high to around EUR 72/MWh.
- Precious metals have trimmed some of their earlier downside as energy prices and global yields fall following the more diplomatic Iranian headlines. Spot gold has recovered from a USD 4,292/oz low to above its 50 DMA (USD 4,316/oz), having earlier reached USD 4,376/oz. Spot silver similarly trades around USD 65.50/oz after falling to a USD 64.57/oz low from a USD 65.81/oz high.
- Base metals remain firmer, with copper supported by the broader positive global risk tone, while the sharp pullback in energy prices provides some relief to the inflation and growth outlook. COMEX copper trades around USD 6.66/lb, near the upper end of its session range. 3M LME copper trades towards the upper end of a USD 14,703.60-14,790.00/t range.
- Saudi Arabia restarts the East-West oil pipeline and prepares to resume crude oil exports from Yanbu port later on Tuesday, according to trade sources.
- Saudi's Aramco has reportedly told Asian refiners that they will be able to pick up oil from Yanbu soon, Bloomberg reported citing sources.
- Libya's NOC said an armed group closed valve 7 on the Sharara crude pipeline to Zawiya port, causing a sharp drop in output at the Sharara oilfield. It was later reported that the Sharara oil field production fell by more than half to about 127k bpd after an armed group shut the pipeline to the Zawiya export terminal.
- Russia's oil exports from Black Sea Novorossiysk Port reportedly surged to 650k bpd in September, +50% M/M, sources suggested.
- Indonesia's nickel hub will cut output as an El Niño-driven drought reduces production.
- Russia's Agriculture Ministry said its grain procurement planned for 2026-27 at 3mln tonnes, IFX reported.
Trade/Tariffs
- Chinese President Xi's most urgent goal during the summit with US President Trump is extending the trade truce with the US, but he is also expected to discuss Taiwan, Iran and AI, according to FT.
- USTR will hold a hearing regarding the Section 301 investigation into Germany's pharmaceutical policies today.
- EU Trade Commissioner Sefcovic is to visit China between October 8th-9th for trade talks.
- Canada's Trade Minister said the country is making great headway in concluding a free trade agreement with India, while they will continue to have talks with the US.
- China's MOFCOM announced the adjustment to the "Catalogue for the Administration of Export of Precursor Chemicals to Specific Countries", stating that export permits will be required for the US, Mexico and Canada under new rules.
- China's MOFCOM said that its Commerce Minister met with the German Auto Industry Association President to discuss bilateral auto cooperation and China-EU trade. MOFCOM said that China is not the root cause of EU trade problems.
Geopolitics
- Russian Kremlin said they are finding alternative routes for their grain and that Ukraine is the reason for the export issues. Discussions with Turkey around the Black Sea have taken place.
- Russian Foreign Minister Lavrov and US Secretary of State Rubio are set to meet on September 23rd, TASS reported.
- Russian Defence Ministry said Russian forces struck an oil refinery in Ukraine’s Kremenchuk, TASS reported.
- Ukraine's Naftogaz said that the Russian attack caused critical damage, which makes it effectively impossible to restore it.
- Polish Army said it commenced military aviation operations in Polish airspace following a Russian aerial attack on Ukraine, although it later announced that military aviation operations in Polish airspace concluded and there was no violation of Polish airspace observed.
- The US will reopen a military base in southern Greenland and establish presence at a second site in eastern Greenland, according to sources.
Event Calendar
DB's Jim Reid concludes the overnight wrap
Markets have put in a strong performance over the last 24 hours, with Brent crude oil (-3.40%) briefly falling beneath $100/bbl again as hopes grew for a diplomatic solution in the Middle East. Brent is a little above $101/bbl this morning but net net the week has started more optimistically. This has been highlighted by the record high for the Nasdaq (+2.26%), Bitcoin moving back above $85,000 for the first time since January, whilst the 10yr bund yield (-6.3bps) had its biggest daily decline since May. And despite September’s reputation as one of the worst of the year for markets, the latest moves actually leave the S&P 500 (+1.49%) back in positive territory for the month and within half a percent of its all-time high.
Although oil is back up a little overnight, Brent fell back beneath $100/bbl yesterday for the first time in nine trading sessions before closing at $100.34/bbl. In part, that followed more positive headlines over the weekend, including comments from President Trump to Fox News that he would be open to meeting Iran’s President at the UN this week. So that raised hopes about some kind of deal between the two sides, and it helped drive a big reduction in energy prices across the board. In fact, European natural gas futures (-7.88%) saw their biggest daily decline since July, which was a huge positive impulse to risk appetite given Europe’s dependence on imported energy. Even though there are hopes of diplomatic progress, the rise back in oil overnight seems to be in part due to Bessent suggesting that all Iranian airlines will be shut down from tomorrow with anyone providing fuel, landing services etc., shut out of the dollar system.
For now the momentum is on the more positive side though and with inflation fears subsiding again, that meant investors dialled back the likelihood of rapid rate hikes, even if plenty are still priced in for the month ahead. For instance, markets are still fully pricing in another ECB hike by year-end, but the probability of a second hike this year fell from 52% on Friday to 40% by the close. The read across from the energy pullback to Fed repricing wasn’t as clear, with 33bps of Fed hikes still priced by year end. That came amid some hawkish-leaning commentary from regional Fed presidents, with Goolsbee suggesting there was some “traditional demand overheating” around the AI investment boom, while Musalem said that the current fed funds rate of 3.75% to 4% is “on the accommodative side”.
Notwithstanding the hawkish Fedspeak, lower energy prices proved to be a huge tailwind for sovereign bonds, particularly in Europe. So yields came down across the continent, with those on 10yr bunds (-6.3bps), OATs (-9.3bps) and BTPs (-9.6bps) all seeing sharp declines. In fact, in all three cases that was their biggest decline since May. In the US, the declines weren’t quite as big, with the 10yr Treasury yield down -4.5bps to 4.95% while the 2yr yield actually inched up +0.3bps to 4.75%. That brought the Treasury 2s10s slope to its flattest since February 2025, just before Trump’s tariff escalation raised questions about the sustainability of US exorbitant privilege.
For equities, it was also a very strong session, as fresh optimism on the outlook led to big gains across the major indices. In the US, the S&P 500 (+1.43%) rose for a third consecutive session and had its best day in seven weeks, leaving the index just -0.44% beneath its record high from last month. Tech stocks led the rally, with the Nasdaq (+2.26%) and the Magnificent 7 (+3.44%) rising to new record highs of the own. Top performers included Meta (+11.43%), amid optimism over its Muse AI agent, and chipmaker AMD (+9.95%), which became the latest company to reach a $1trn valuation. Meanwhile, there were broad gains in Europe, where the STOXX 600 (+1.02%), the DAX (+1.07%) and the CAC 40 (+0.92%) all climbed.
Speaking of geopolitical developments, there were plenty of headlines on the US-China trade talks yesterday, ahead of the meeting between Presidents Trump and Xi later this week. For markets, the big question is what’s going to happen when the current one-year trade truce expires in November, and whilst the general tone remains positive, there still isn’t an agreement yet. For instance, the New York Times reported yesterday that the US had proposed a 6-month extension, whilst China had pushed for a longer one. So that fitted with comments from US Trade Representative Greer on Bloomberg, who was asked if it would be a 3-6 month extension, and he said “that’s probably the right kind of range”. Otherwise he sounded positive though, saying that “we’ll continue talking and I think both sides want it”.
Ahead of the Trump-Xi meeting, our geopolitical analysts, economists and strategists are hosting a China macro webinar at 9am LDN today. You can register here.
Otherwise, the big political news came from Germany yesterday, where there was plenty of reaction after Sunday’s state election results. As a reminder, that vote saw Chancellor Merz’s CDU party fail to meet the 5% threshold in the state of Mecklenburg-Western Pomerania, meaning they’re not in the regional parliament for the first time in Germany’s post-war history. Yet despite the speculation over Merz’s position, he said that he had the backing of CDU party leaders, and that both the CDU and SPD wanted the governing coalition to continue.
Asian equity markets are broadly higher this morning, led by technology stocks as an overnight rally on Wall Street reignited investor appetite for AI-related stocks. Across the region, the KOSPI (+0.69%) is leading gains, while Japanese markets remain closed through Wednesday. Elsewhere, China’s CSI 300 (+0.51%) is trading moderately higher, with the Shanghai Composite (+0.23%) and Hang Seng (+0.33%) posting modest advances. Meanwhile, Australia’s S&P/ASX 200 (+0.29%) is also edging higher. US equity futures are fairly flat.
Looking at the day ahead now, data releases include the UK public finances for August, the European Commission’s preliminary consumer confidence reading for the Euro Area in September, and the US Richmond Fed’s manufacturing index for September. Otherwise from central banks, we’ll hear from Fed’s Vice Chair Jefferson, the Fed’s Williams and Barkin, ECB President Lagarde, and the ECB’s Kaasik, Nagel, Kocher, Seijpen and Simkus.