TSLA Jumps To 3-Month Highs After Big Margin, Free-Cash-Flow Beat
Having rallied over 3% on the day - on the back of SPCX-TSLA merger talk - Musk's other company is swinging wildly (mostly higher) after hours after printing better the Street was braced for on profitability and cash-flow, worse on the top line, and still consistent with a company spending heavily on AI, robotaxi, and Optimus while the core vehicle business stays roughly flat.
The Goods...
The margin recovery is real. Gross margin at 19.6% is a clear beat (17.8% exp) after Q2’s weak print, and the auto margin ex-credits recovered to 18.1%.
Services continues to grow quickly and is now a meaningful contributor.
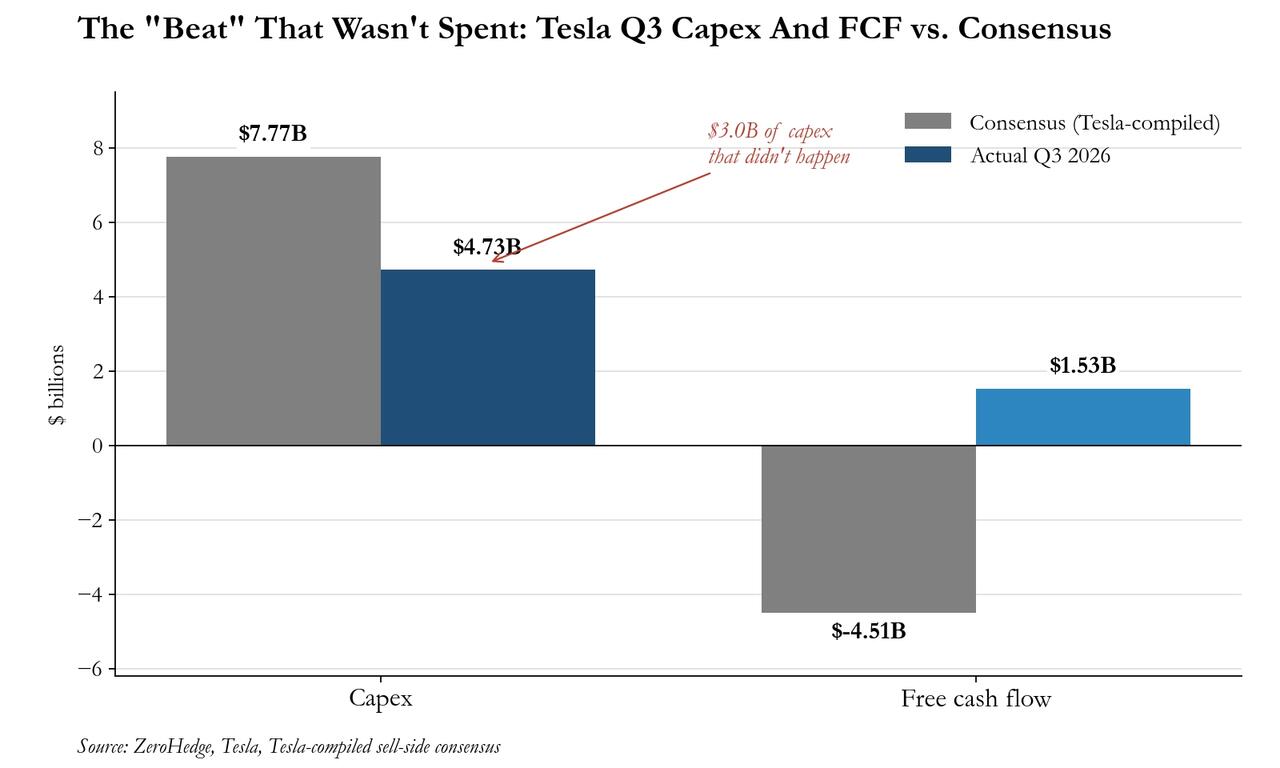
Most importantly for the near-term tape, free cash flow swung positive to +$1.53B instead of the $4.99 billion burn the Street had modeled.
That happened largely because CapEx came in much lower than expected this quarter ($4.7B vs ~$7.8B).
Tesla still has a large cash pile.
The Not-So-Goods
Revenue is flat year-over-year despite the delivery beat.
Energy revenue declined.
GAAP earnings remain soft, and the gap between GAAP and non-GAAP continues to rely on the usual adjustments (stock-based compensation, digital asset marks, the SpaceX equity stake, etc.).
Operating margin is still only 2.6% - better than last quarter but nowhere near historical levels.
Operating expenses jumped 39% YoY to $4.78 billion, with R&D alone up 69% to $2.76 billion.
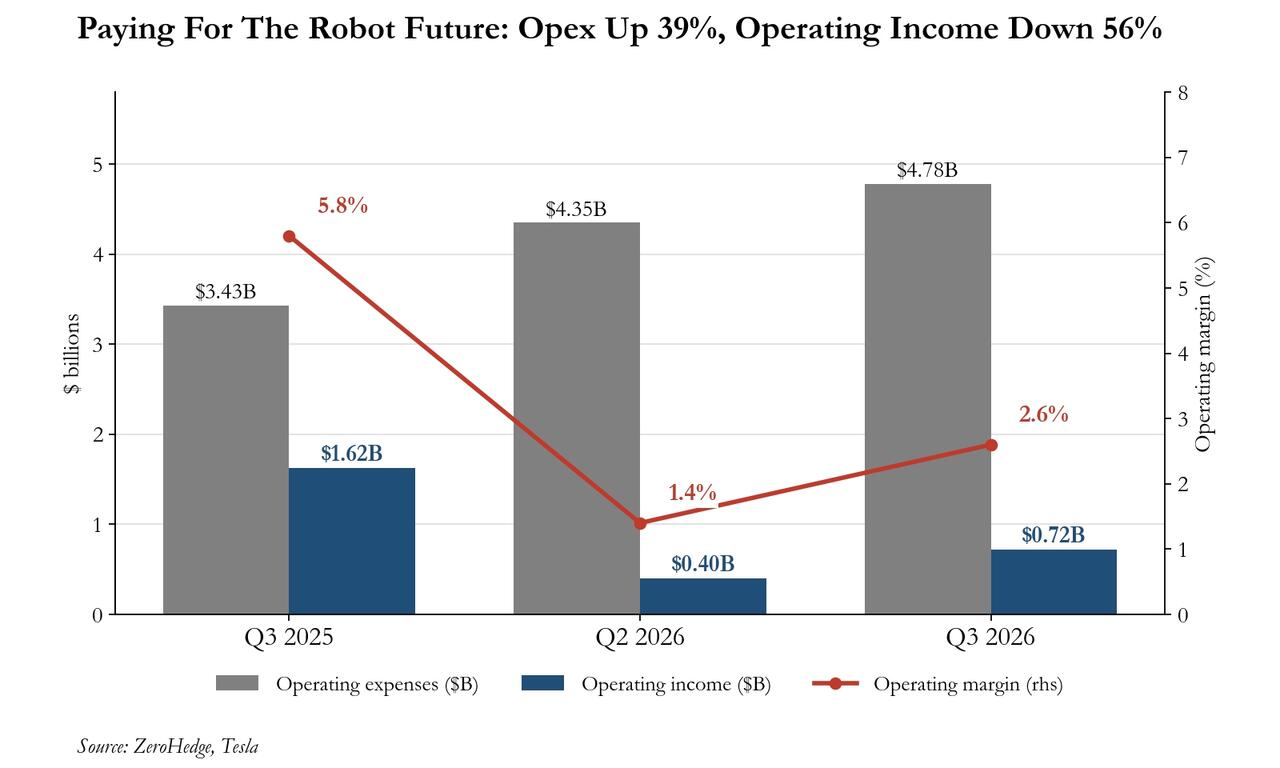
The company is still in a heavy investment phase for AI compute, Cybercab/robotaxi, Optimus, and related capacity.
One quarter of lower-than-expected CapEx does not change the multi-year spending trajectory Tesla has guided.
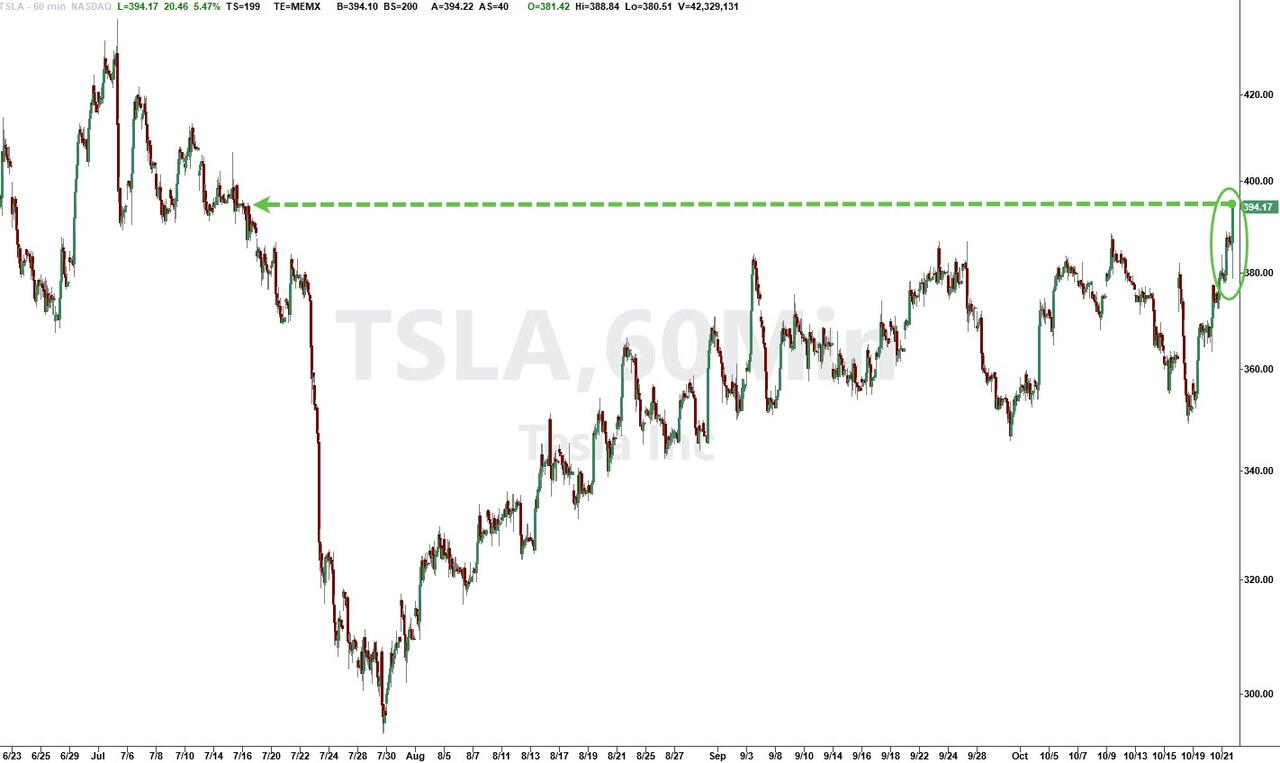
At the time of writing - before the conference call - TSLA shares are extending the day's gains, now trading at its highest since July...
Of course, what really matters with this stock is what Musk says during the call at 1730ET
The numbers are mixed enough that the stock’s reaction will hinge on what he says about:
-
Robotaxi / unsupervised FSD timelines and progress
-
Optimus production and any commercialization path
-
Capex trajectory for the rest of 2026 and into 2027
-
Any update on the SpaceX special committees / potential combination
Tesla remains a high-multiple narrative stock trading on future optionality (robotaxi, Optimus, AI) rather than current free cash flow or earnings power.
The margin and FCF beats give the bulls cleaner numbers to point at than Q2.
The flat revenue, still-depressed GAAP profits, and ongoing heavy investment give the skeptics their usual ammunition.
As always with this name, the narrative usually wins in the short term, as the optimists will say none of that matters if Tesla becomes the earthbound arm of a $3.5 trillion Musk conglomerate.
And they may be right, at least until the merger math has to be done in a proxy statement. But a company that needs to spend $12 billion in one quarter to hit its own CapEx target, while its legacy cash cow (regulatory credits) dies, is going to need SpaceX a lot more than SpaceX needs it.